


Author
Ben Jastatt
Sr. Director, Marketing
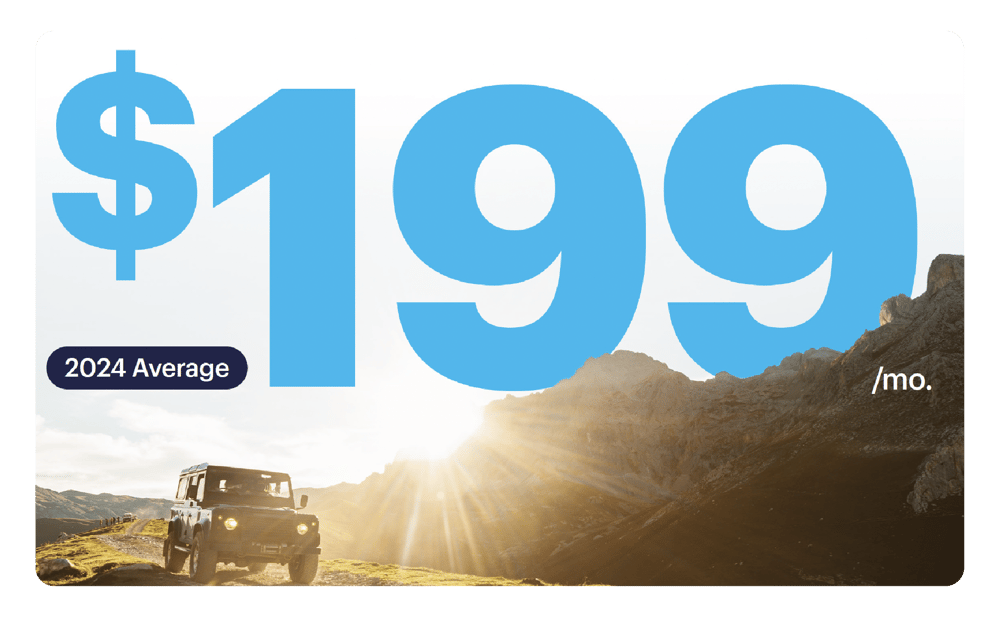
The average in-dealership auto insurance quote averaged around $200 per month throughout 2024, topping off at an average of $202 per month in Q4.
While this is good news, quotes are still creating price shock for many consumers, as it still represents an increase of more than $60 per month in the last two years. And quotes in higher cost states are 50% or more above the average 2024 rate, creating an affordability crisis for many car buyers and disrupting car sales for dealers.
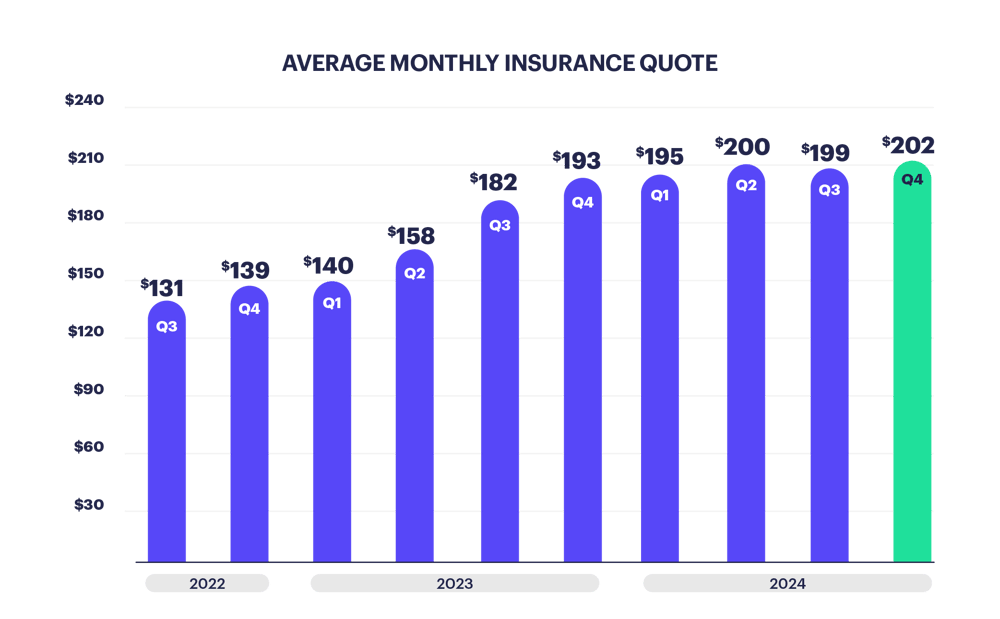
This represents an 18% YOY increase from 2023, far outpacing the overall rate of inflation, and eclipsing changes in the consumer price index for new and used vehicles, which declined in 2024 by 0.4% and 3.3% respectively.*
As rates have risen, consumers are shopping for insurance more than ever. Meanwhile, the market has become more competitive, with a greater number of insurance companies onboarding new business than in previous years.*
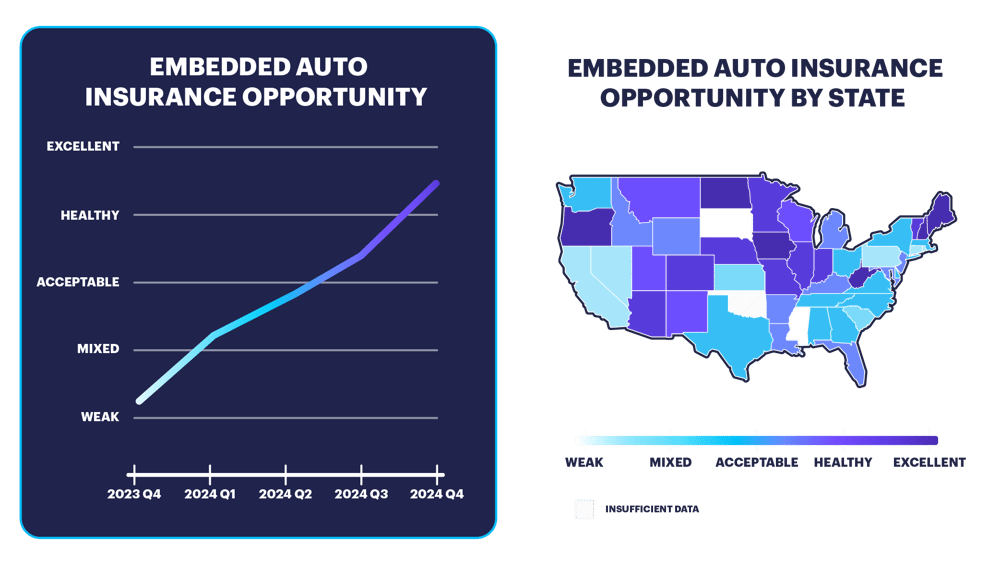
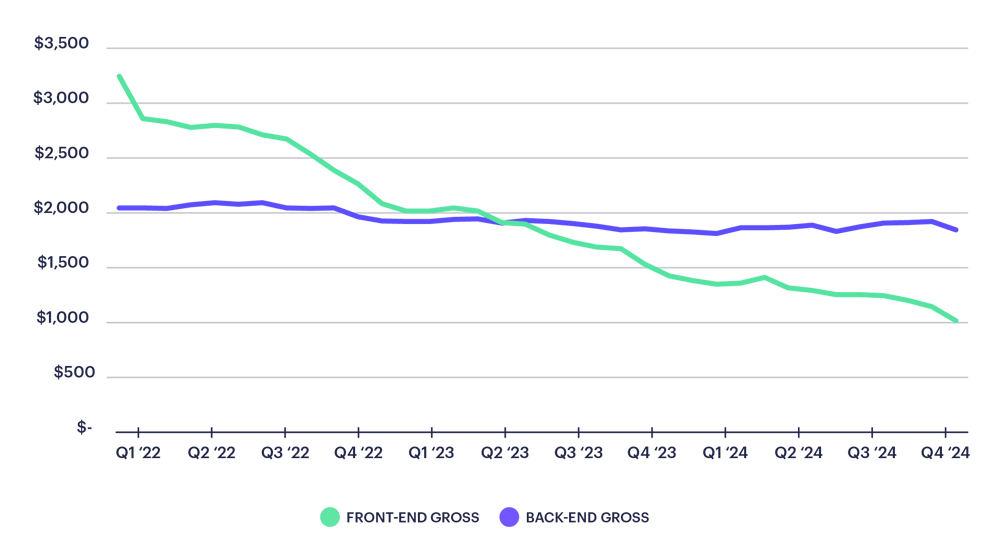
This decline is driven by increased auto inventory* and declining affordability.**
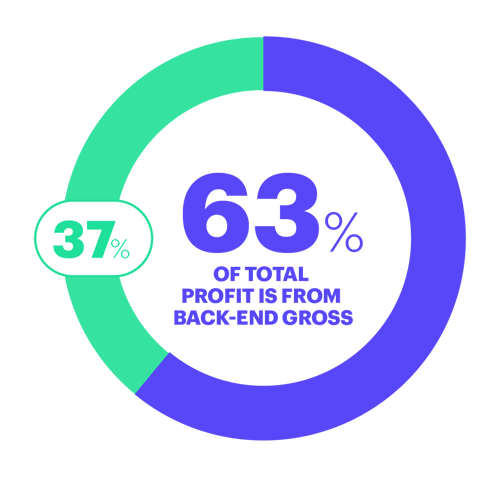
However, back-end gross has remained constant for all of 2024, hovering within $55 of the average of $1,868 for the full year.
*nada.org/nada/research-and-data/market-beat
**newsroom.aaa.com/2024/09/aaa-your-driving-costs-the-price-of-new-car-ownership-continues-to-climb/
In Q4, all our top ten most engaged dealer groups continued to see higher back-end gross with insurance, in line with the averages seen during the first three quarters of the year.
Fluctuation between groups is largely a function of average F&I penetration at each dealership.
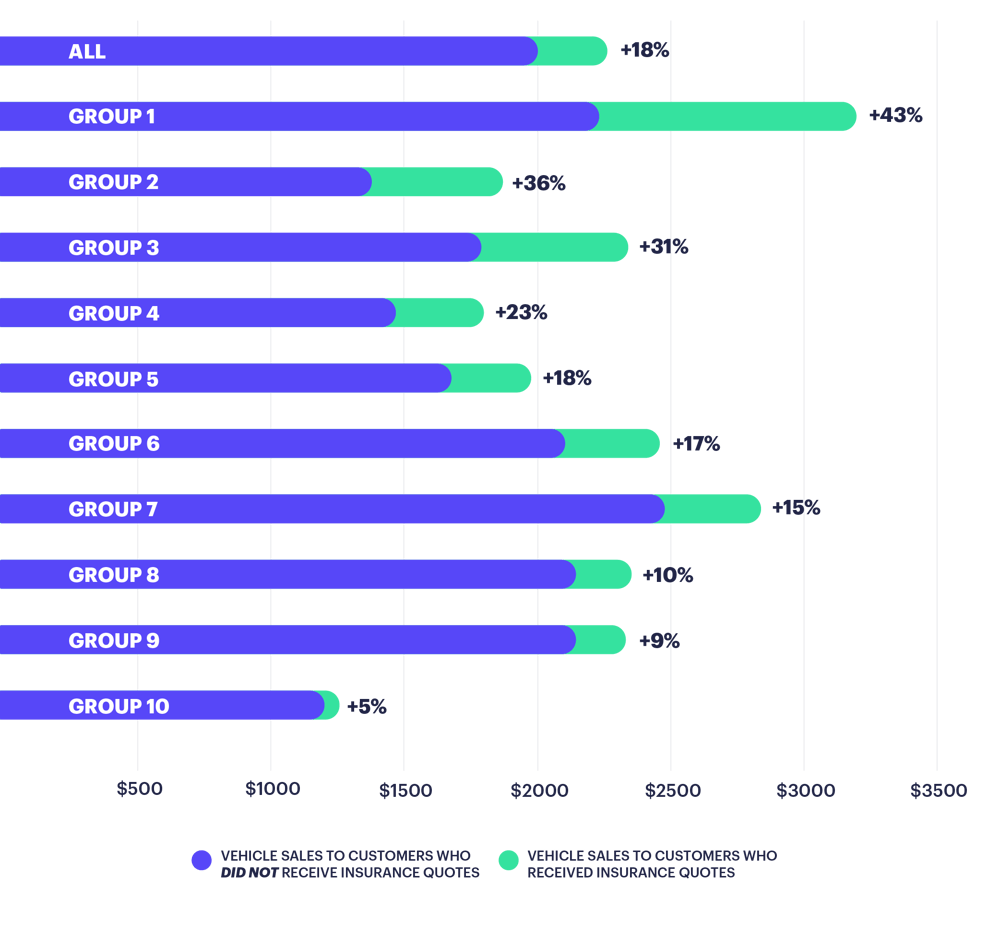
Includes only High-Polly-Engagement dealerships (at least 50 quotes and quoting at least 2% of transactions) over the past 12 months.