Skip to content
Demo Polly
Contact Us

After the low-point of 2023 and steady recovery in 2024, the embedded auto insurance market is gaining strong momentum in 2025.

We measure this growth by tracking buyer intent at the dealership, overall policy purchases, and then adjust for customer mix and insurer appetite for new business.

By that measure, the opportunity has nearly tripled since its lowest point in late 2023.

As more insurance companies return to the market and loosen their underwriting criteria, more buyers are finding affordable insurance options at the point of sale.

For dealers, this trend is highly encouraging: more insurance options for customers often translates into customer savings in the dealership and even more closed deals. That can lead to higher F&I gross. This effect is covered later in the report with an analysis of our top 10 most engaged dealerships.

In 2025, the embedded opportunity continues to accelerate. And for dealers already leaning in, the results are clear.
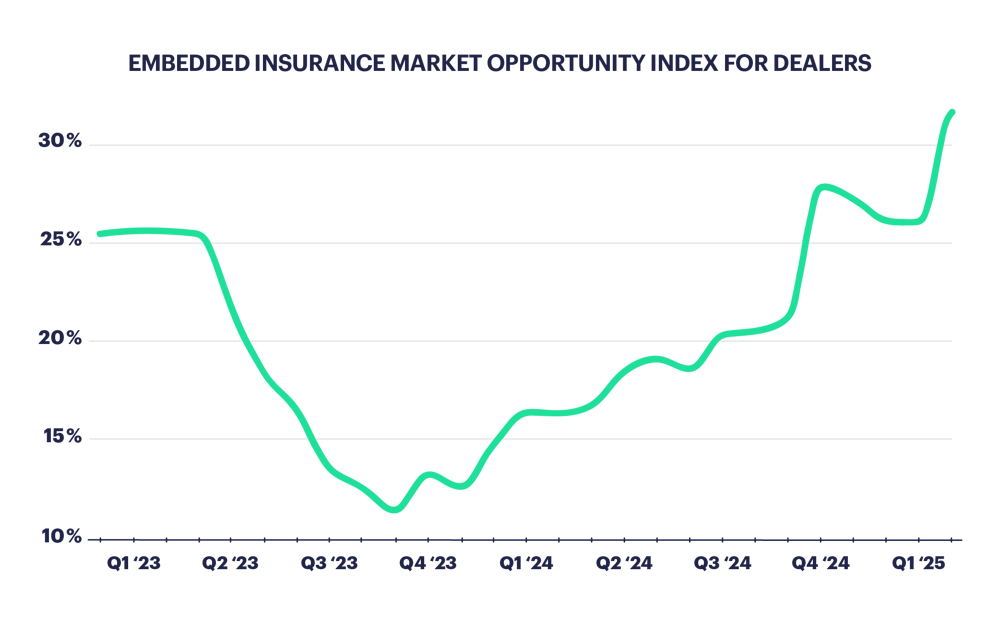
Line chart: Embedded Insurance Market Opportunity Index for Dealers falling from about 25% in Q1 2023 to about 12% in Q4 2023, then rising to about 31% in Q1 2025

21% Higher F&I Gross Profit with Insurance Quotes

Dealerships that consistently engaged car buyers in the insurance quoting process saw a significant lift in profit.

Among our top 10 most engaged dealer partners, the average F&I gross was 21% higher when customers merely saw insurance quotes (without even purchasing insurance). That simple action translated into an average increase of $320 higher F&I gross profit per deal.

But the impact doesn’t stop at quoting. When customers actually purchased a policy, they saw an even greater improvement to F&I gross of 28% or $432 per deal.

These findings reinforce a clear trend: integrating insurance into the car-buying experience not only enhances customer value, but it also directly increases dealership profitability. Whether customers save or not, offering embedded insurance drives higher trust, stronger engagement, and more room to maximize F&I opportunities.
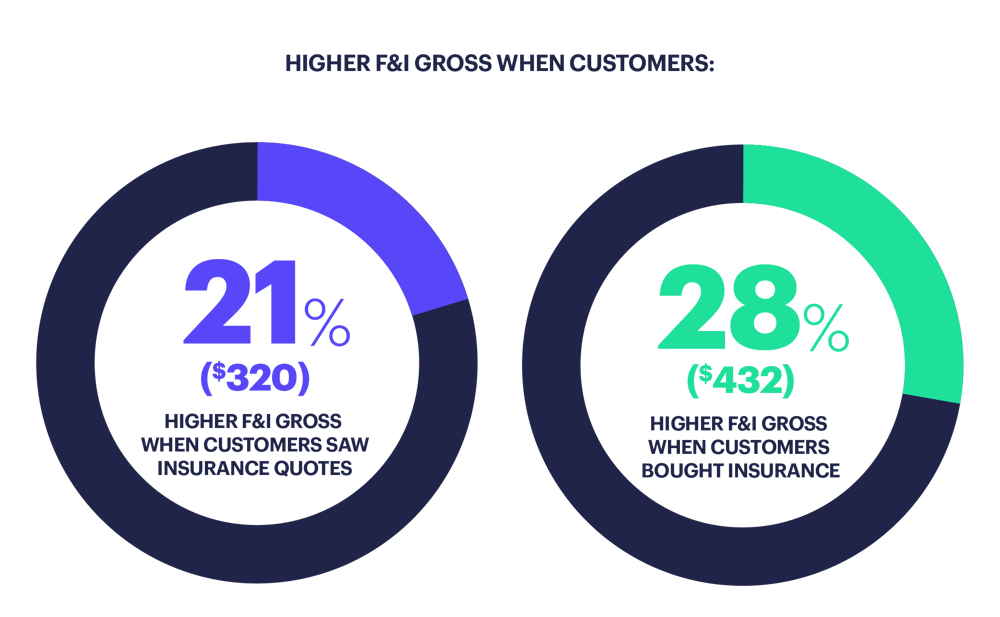
Higher F&I gross when customers saw insurance quotes (21%, $320) and bought insurance (28%, $432)

View the data behind this chart
Higher F&I gross when customers saw insurance quotes or bought insurance, Q1 2025
Customer actionIncrease in F&I grossDollar increase
Saw insurance quotes+21%$320
Bought insurance+28%$432

From Polly’s Q1 2025 Quarterly Embedded Auto Insurance Report.

Insurance and F&I Gross Across Top 10 Dealerships

In Q1, all of Polly’s top ten most engaged dealer groups* continued to see higher back-end gross with insurance, for the fifth straight quarter, we’ve reported on this metric. This graph includes a blended average of F&I gross for customers who received quotes but didn’t buy insurance as well as customers who bought insurance.
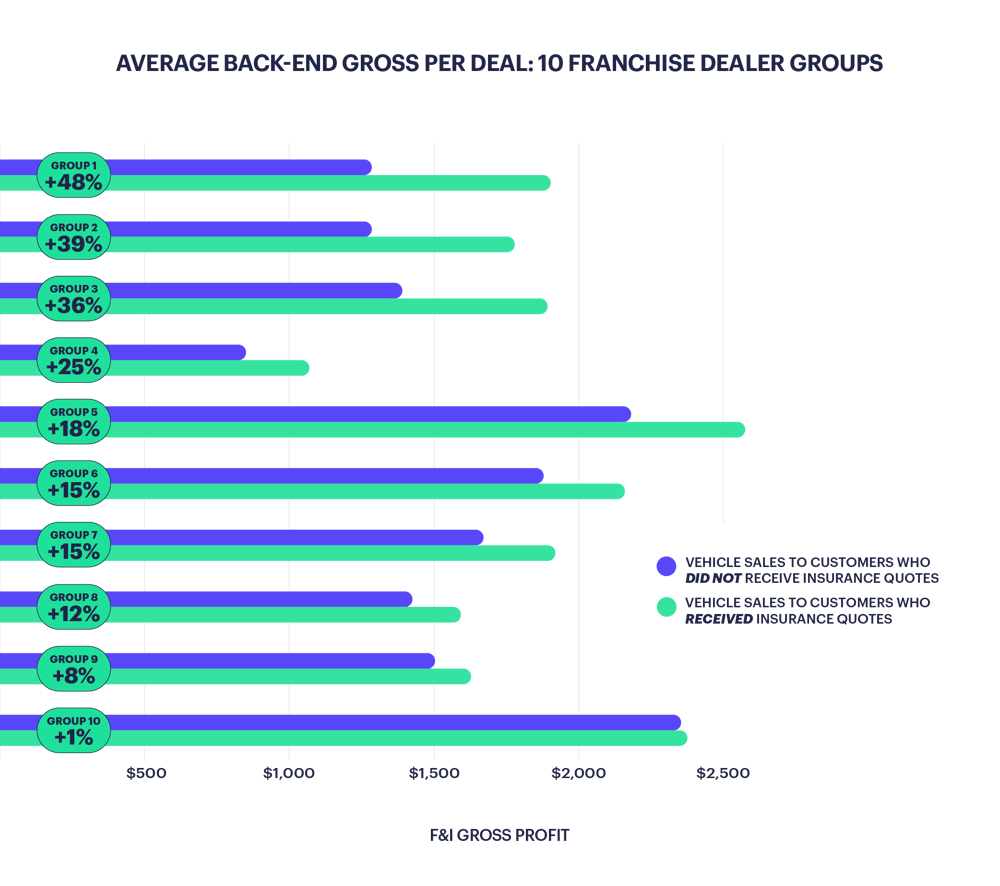
Bar chart: average back-end gross per deal for 10 franchise dealer groups, with insurance quotes lifting F&I gross from 1% to 48%

View the data behind this chart
F&I gross lift with insurance quotes at 10 franchise dealer groups, Q1 2025
Dealer groupBack-end gross lift with insurance quotes
Group 1+48%
Group 2+39%
Group 3+36%
Group 4+25%
Group 5+18%
Group 6+15%
Group 7+15%
Group 8+12%
Group 9+8%
Group 10+1%

From Polly’s Q1 2025 Quarterly Embedded Auto Insurance Report.

Why Insurance Quoting Matters So Much

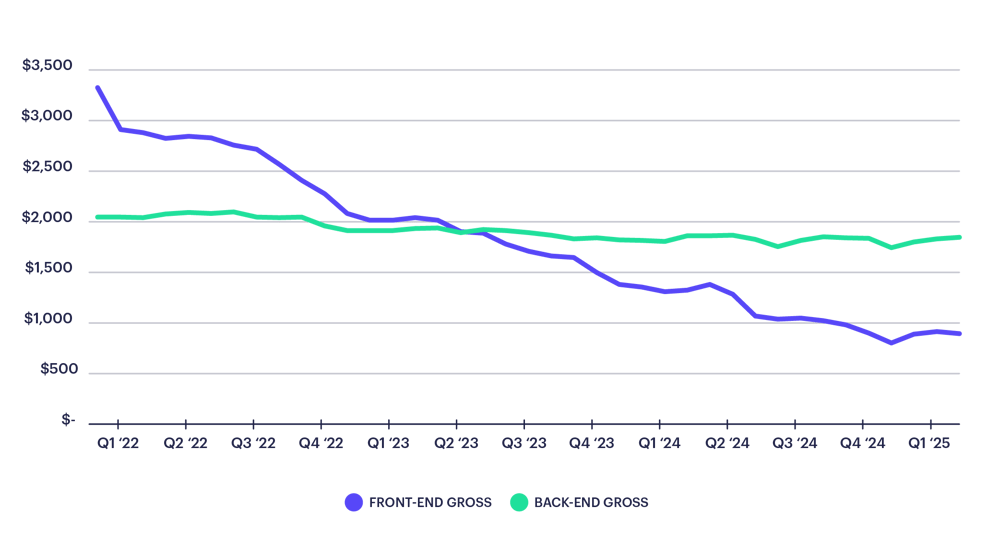
F&I gross profit is now two times higher than front-end gross.

Front-end gross fell under $1,000 ($970 actual) in Q1, down 30% year over year. However, F&I gross profit has remained consistent over the last two years, coming in at $1,839 for Q1.

With front-end gross compressing, the F&I office has become the last stronghold of dealership profit.

As dealers rely more heavily on back-end products, embedded insurance can help them maintain F&I profitability.

Average F&I Gross Profit Q1 2025

$1,839

Line chart: front-end gross falling from about $3,300 in Q1 2022 to under $1,000 in Q1 2025 while back-end gross holds near $1,800 to $2,000

Insurance Rates Ease in Q1 2025 to an Average of $195 per Month

$195 Average Monthly Polly Insurance Quote for Car Buyers

After a long period of steep insurance increases, auto insurance prices started to cool in Q1 2025. Polly’s findings matched the overall consumer price index which showed an 0.8% drop month over month for the end of March.*

The median monthly Polly insurance quote for car buyers shopping in-dealership dropped to $195, a slight decline from the Q4 2024 high of $202.

For dealers and their customers, that’s good news, especially in a market where affordability can make or break a deal.
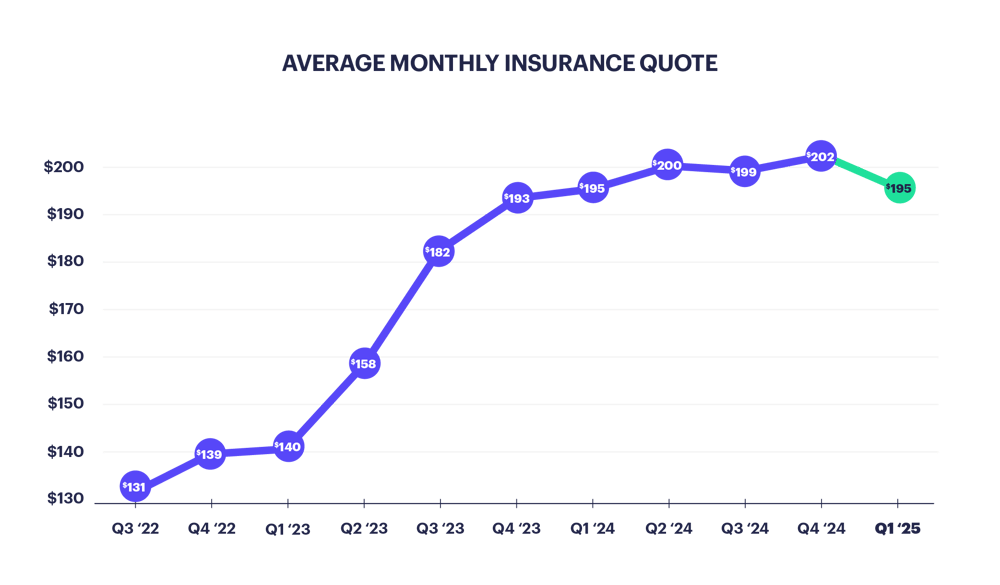
Line chart: average monthly insurance quote rising from $131 in Q3 2022 to a high of $202 in Q4 2024, then easing to $195 in Q1 2025

View the data behind this chart
Average monthly insurance quote, Q3 2022 to Q1 2025
QuarterAverage monthly quote
Q3 2022$131
Q4 2022$139
Q1 2023$140
Q2 2023$158
Q3 2023$182
Q4 2023$193
Q1 2024$195
Q2 2024$200
Q3 2024$199
Q4 2024$202
Q1 2025$195

From Polly’s Q1 2025 Quarterly Embedded Auto Insurance Report.

Insurance Market Friction Decreases

Many car buyers faced limited or high-cost insurance options in 2023 and 2024, but the market has shown a sustained return to healthier dynamics.

As of early 2025, fewer buyers are encountering barriers, and 19 out of 20 are seeing highly competitive quotes.

This recovery follows a peak in late 2023 when more than 1 in 6 buyers experienced high-friction conditions. Since then, quote availability has steadily improved, suggesting insurer appetite is returning and market conditions are stabilizing.
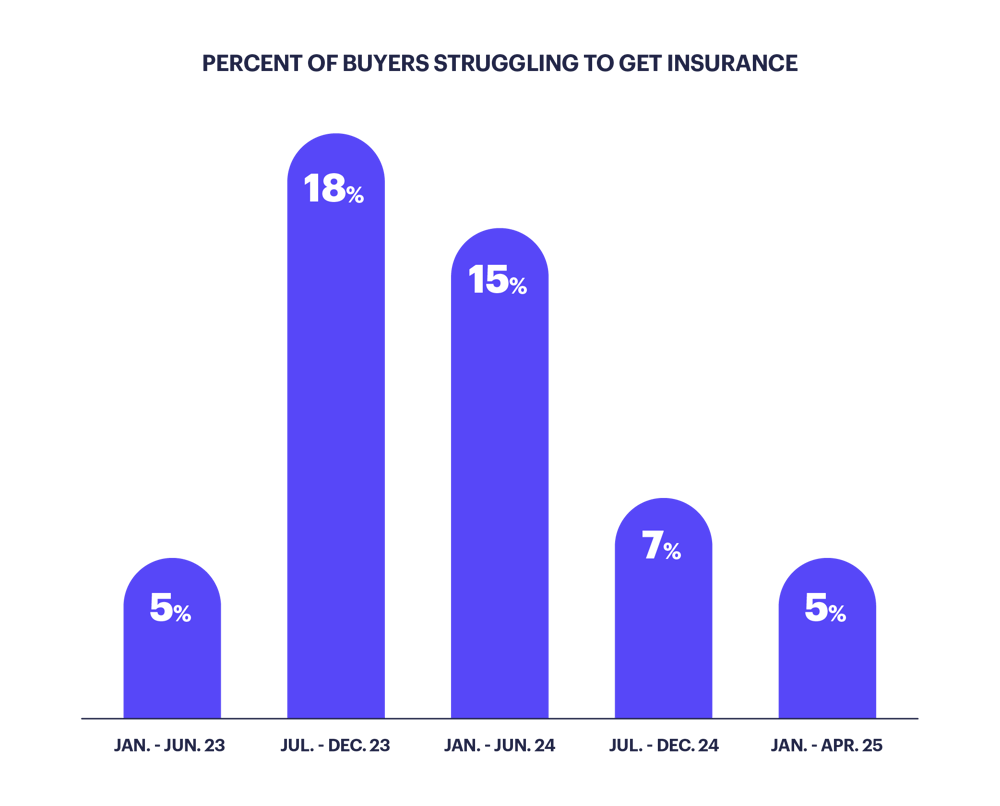
Bar chart: percent of buyers struggling to get insurance rose from 5% (Jan to Jun 2023) to 18% (Jul to Dec 2023), then fell to 5% (Jan to Apr 2025)

Percent of buyers who were either uninsurable, had high insurance (more than 2X monthly average), or faced conditions where insurance companies pulled back from taking on new customers in their states.

View the data behind this chart
Percent of buyers struggling to get insurance, Q1 2025 report
PeriodShare of buyers
Jan to Jun 20235%
Jul to Dec 202318%
Jan to Jun 202415%
Jul to Dec 20247%
Jan to Apr 20255%

From Polly’s Q1 2025 Quarterly Embedded Auto Insurance Report.

Highest Insurance Costs Impacting Affordability Across Most States

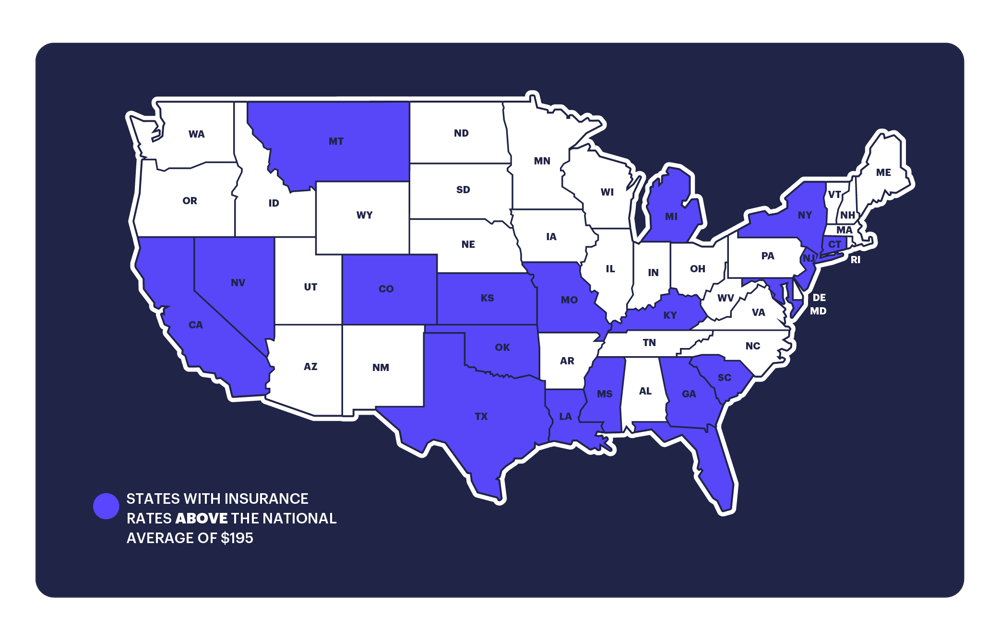
Map of states with insurance rates above the national average of $195

The national average quoted auto insurance rate in Q1 2025 was $195 per month.

Kentucky, New York, Mississippi, Nevada, and Washington were the top 5 most expensive states to insure in Q1. Elevated costs can introduce unexpected friction into the car-buying process, impacting monthly payment calculations and even derailing deals.

For dealers in these high-cost states, integrating insurance earlier in the sales process can be a crucial closing strategy.

By surfacing accurate quotes upfront, dealers can help manage expectations, uncover savings opportunities, and keep more deals on track.

Predictions: What to Expect in the Months Ahead

1. Embedded Opportunity Will Continue to Climb

We expect to see another strong upswing in our embedded insurance index in Q2 2025. As more insurers re-enter the market and their appetite expands, dealers who embrace embedded insurance will be in the best position to convert more sales, increase F&I profit, and deliver a better customer experience. With profits from car sales in decline, dealers will need to look to other levers like insurance to preserve and grow profit.

2. Insurance Will Continue to Be a Part of the Affordability Conversation

Insurance prices are beginning to ease, but affordability will remain top of mind for consumers, especially in high-cost-to-insure states. We anticipate that insurance quoting will become an even more routine part of the car-buying process, not just for savings but for deal structure and customer confidence.

3. Economic Uncertainty Could Disrupt Insurance Prices

The full impact of tariffs on imported auto parts hasn’t been felt yet. Rising repair costs may force insurers to seek rate increases later in the year, but those changes will take time to move through regulatory channels. We could see price volatility return in certain markets by late 2025 or early 2026.

4. Climate Risk Will Pressure Select Markets

Year-round extreme weather events are putting continued strain on insurers’ risk exposure in some markets. We anticipate more selective underwriting in high-risk areas, meaning some car buyers could face limited or more expensive coverage. Dealers in affected regions should be prepared to navigate higher friction in the insurance process.

Start Growing with Polly

Let embedded auto insurance be your dealership's next growth tool.

Get Embedded